

MAJORITY: Mobile banking
MAJORITY USA, LLC
- 4.8
- 8.98K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
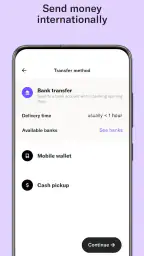
MAJORITY: Mobile banking Pros and Cons
Pros
- User-friendly interface simplifies transactions.
- Instant notifications for account activity.
- Supports multiple accounts management easily.
- Secure login with biometric authentication.
- Free ATM withdrawals from partner banks.
Cons
- Limited customer support availability.
- Occasional app crashes disrupt usage.
- Few budgeting tools for financial planning.
- High fees for international transfers.
- No desktop version available for use.
 Analysis by All-app
I judge a banking app less by the excitement of opening it than by whether it still helps once the first-week novelty wears off. MAJORITY has a clear reason to earn a place on your phone: it brings a U.S. account and debit card together with services aimed at people managing money across borders. That focus can be genuinely useful, though it does not make the app a perfect replacement for every bank or money-transfer service.
Who is most likely to find it useful?
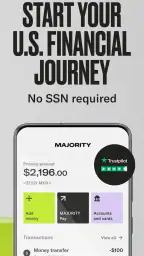
I would look closely at MAJORITY if I were settling in the United States and needed a financial starting point without a Social Security number. The app is a finance product from MAJORITY USA, LLC, and its central appeal is practical rather than flashy: a way to get an account and debit card, with international transfers available alongside everyday money management. The age rating is Everyone, and the app is free to download.
That does not mean the same setup suits every newcomer. Having an account option without an SSN can remove a major obstacle, but a person still needs to check the app’s current eligibility and identity-verification steps before depending on it. I would treat account opening as a process to complete before an urgent payday or bill deadline, not something to begin at the last minute. A smooth sign-up is valuable; a rushed sign-up creates avoidable stress.
How it fits beside other money tools
Compared with a conventional bank app, MAJORITY has a more specific job: it puts U.S. banking access and international money needs in the same place. Compared with a transfer-only app, it aims to be useful between transfers too, because the account and debit card are part of the proposition. That combination is the reason to consider it, rather than assuming it will beat every bank on every banking feature or every remittance service on every destination and rate.
I would compare the complete routine, not just a headline exchange rate. Think about how you receive money, where you need to spend it, and how often you send funds abroad. If your main need is an established domestic bank relationship, a local bank or credit union may be a better fit. If you only send an occasional transfer and already like your current account, a dedicated remittance provider may be simpler. MAJORITY makes the most sense when its different roles solve the same person’s recurring problems.
A useful way to test it
Before making it your primary account, I would use a small, ordinary task to see whether the whole path works for me: complete registration, understand how to use the debit card, and learn where transfers sit in the app. Then I would check that the timing and steps fit my actual routine. This is more revealing than browsing features. It shows whether the app is convenient for the things I do repeatedly, not merely interesting on the day I install it.
A realistic example is someone who has just moved to the U.S., gets paid into an account, uses a debit card for weekly purchases, and sends money to family abroad when the budget allows. A single app could make that routine easier to follow, but the person should still plan around transfer timing and keep enough money available for local expenses. I would not send the entire balance abroad simply because the transfer option is easy to reach; convenience should not replace a basic cash-flow plan.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What Makes MAJORITY Stand Out?
Picture this: you’re new in town, trying to establish yourself, and the last thing you need is a complicated banking process. That’s where MAJORITY comes in. Designed with immigrants in mind, it’s more than just a banking app; it’s a financial companion. From setting up an account without the traditional requirements to offering resources that help you adapt to a new country, it’s like having a friend who knows the ropes.
Getting Started
Signing up is as breezy as a Sunday morning. No social security number? No problem! You just need to be living in the U.S. and have a valid ID. The app guides you through the process with ease, and before you know it, you’re set up and ready to go. It’s like magic, but better because it’s real.
Features You’ll Love
Let’s talk features, shall we? MAJORITY offers fee-free cash deposits and withdrawals at over 55,000 locations. Yes, you heard that right. Plus, you’ll get access to an international calling feature that doesn’t make your wallet cry. Need to send money back home? The app’s got your back with competitive exchange rates. And, oh, did I mention the in-app resources to help you learn English and connect with local communities? It’s like they’ve thought of everything!
User Experience
Using the app is smoother than a hot knife through butter. The interface is clean and intuitive, perfect if you ask me. You don’t have to be a tech wizard to find your way around, which is a huge relief. Everything you need is right at your fingertips, from checking your balance to making international calls.
Why I Think It’s Worth a Shot
In a world where traditional banking often feels like a maze, MAJORITY offers a straightforward path. It’s not just about managing money; it’s about making life simpler and more connected. Whether you’re an immigrant or someone looking for a hassle-free banking experience, this app has something for everyone.
So, if you're tired of the usual banking blues and want something that truly understands your needs, give MAJORITY a try. Who knows? It might just become your new favorite app.
Keeping it useful after the first week
The first week is when an account app can feel most impressive: you have a new card to set up, options to explore, and a clearer picture of what it can do. The longer test is whether those functions map to habits you already have. I would keep MAJORITY in regular rotation only if I were using its account for real spending or relying on its cross-border services often enough to justify another financial app on my phone.
That distinction matters because a collection of services is not automatically a simpler life. If you already have a reliable way to bank, call family, and send money, switching everything at once may add more work than it removes. A measured approach is better: choose one recurring task where the app could help, use it consistently, and then decide whether the other tools are worth folding into the same routine.
Small habits that reduce friction
I would make a habit of checking the available balance before a transfer and keeping everyday spending money separate in my own budget, even if both tasks happen through one account. That simple pause helps avoid treating the full balance as spare cash. For someone paid on a regular schedule, setting a personal reminder to review bills and planned family support after payday can also make transfers more deliberate instead of reactive.
Cash access is another practical point to think through. The app’s feature set includes fee-free cash deposits and withdrawals at a large network of locations, but I would still identify a convenient location before relying on cash access during a busy week. A network is only useful when its locations fit your commute and opening hours. Checking that in advance is a small step that can prevent a trip across town for a task you assumed would be nearby.
What to verify before relying on it
People often want to know whether “no SSN” means there are no verification requirements. I would not read it that way. The account is presented as available without an SSN, while identity checks can still be part of opening a financial account. Have the identification you intend to use ready and follow the in-app instructions carefully. If a deadline depends on approval, allow time for the process rather than assuming access will be immediate.
International transfers also deserve a little attention before the first send. I would check the destination, the amount the recipient is expected to receive, and any timing shown in the app before confirming. Exchange rates can change, and the best choice depends on the specific transfer and the alternatives available to you at that moment. A rate described as competitive is not a promise that it will always be the cheapest option, so comparing a typical transfer with your usual provider is a sensible one-time check.
It is also fair to ask whether the app replaces a full-service bank. I would not assume that it does. Its appeal is the mix of U.S. account access, a debit card, and international-oriented services; someone who needs a particular banking product, a local branch relationship, or a feature not central to that mix should compare other providers before moving their main finances. The right answer depends on what you need to do every month, not on how many features fit on one screen.
When the extra services help—and when they distract
International calling, language-learning resources, and community connections give the app a broader role than a basic balance-checking tool. Those additions could be valuable to someone building a life in a new country, especially when financial tasks and settling-in tasks overlap. But they will not matter equally to everyone. If you do not need them, they should not be the reason to keep the app; recurring banking value has to carry its own weight.
This is where personal fit becomes clearer over time. Someone who makes regular calls abroad and sends money to relatives may appreciate having those needs close to the account. Someone who already uses a separate calling plan and transfers money only once in a while may find that the bundled idea is less useful in practice. I would judge the app by how much effort it saves in my real week, not by the number of services I might use someday.
Maintenance, trust, and staying organized
Any financial app asks for a little ongoing attention. I would keep my contact and account details current, review transactions often enough to recognize my own activity, and install updates when they are available. These are ordinary habits, but they matter more when one app sits between day-to-day spending and money sent abroad. I would also keep a separate record of important bills and transfer plans instead of relying on memory or assuming an app will manage my household budget for me.
MAJORITY has been available since April 26, 2019, and its current version is 4.0.0, with a minimum operating-system requirement of version 9. Its average rating is 4.8 from around 17,000 ratings, and it has more than a million installs. Those figures suggest that it has reached a substantial audience, but they cannot tell me whether its current features fit my particular needs. I would use them as context, then make the decision based on the account process, the services I actually use, and how the app feels in my monthly routine.
Who should keep looking?
I would hesitate to recommend it as a main option to someone who only wants a plain domestic checking experience and already has one that works well. I would also compare carefully if the most important requirement is a specific transfer destination, a particular service, or the lowest possible cost on every transaction. A broad app can be convenient, but a specialist may be better for a narrow need, and an established bank may be more appropriate for someone who values its particular account options or local support.
On the other hand, for a newcomer who needs a way into U.S. banking without an SSN and expects to use a debit card while staying connected with people abroad, the combination is easier to understand. The strongest reason to try it is not that it does everything; it is that several needs may belong to the same stage of life. If those needs continue month after month, the app has a stronger case for staying installed.
Does it earn a lasting place?
MAJORITY is free, rated for Everyone, and has an average rating of 4.8 across around 17,000 ratings, but I would not keep a money app just because it has a strong public score. I would keep it if it reliably supports the routine I need: access to a U.S. account and debit card, plus services that make regular cross-border life easier. If I stopped using those parts, I would reassess rather than letting unused tools accumulate on my phone.
My lasting verdict is that this is a focused option for people whose banking needs include more than local purchases. Its value comes from fitting account access, a card, transfers, and settling-in resources into one place, while its trade-off is that the bundle may be unnecessary for someone with simpler needs or a preferred provider already in place. I would try it with a clear use case, verify that its current terms and workflow suit me, and let repeated usefulness—not first-week excitement—decide whether it stays.
Frequently Asked Questions
What is MAJORITY: Mobile Banking?
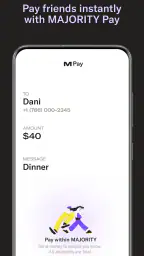
MAJORITY: Mobile Banking is a comprehensive financial application designed to offer essential banking services directly from your mobile device. It provides users with the ability to manage their finances effectively, including sending and receiving money, paying bills, and accessing various financial tools. The app is tailored for ease of use and is a great option for those looking to streamline their financial management on-the-go.
Is MAJORITY: Mobile Banking safe to use?
Yes, MAJORITY: Mobile Banking prioritizes user security and employs advanced encryption technologies to protect your financial information. The app includes features such as two-factor authentication and biometric login options to ensure that your data remains safe and secure. Regular updates and security patches further enhance protection against potential threats.
What features does MAJORITY: Mobile Banking offer?
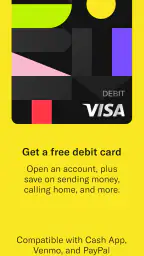
MAJORITY: Mobile Banking offers a wide range of features designed to simplify financial tasks. Users can enjoy services like international money transfers, mobile deposits, bill payments, and access to a free debit card. Additionally, the app provides budgeting tools and spending insights to help users manage their finances more effectively.
How does MAJORITY: Mobile Banking support international transactions?
MAJORITY: Mobile Banking supports international transactions by allowing users to send money to various countries with competitive exchange rates and low fees. The app is designed to facilitate easy and fast transfers, making it ideal for users who need to send money abroad regularly. It also supports multiple currencies, ensuring a seamless experience for international users.
Who can use MAJORITY: Mobile Banking?
MAJORITY: Mobile Banking is available for anyone who meets the basic requirements, such as having a valid ID and being of legal age to open a bank account. The app is particularly beneficial for immigrants and international students, offering tailored services that address their unique financial needs. It is available for download on both Android and iOS platforms.


